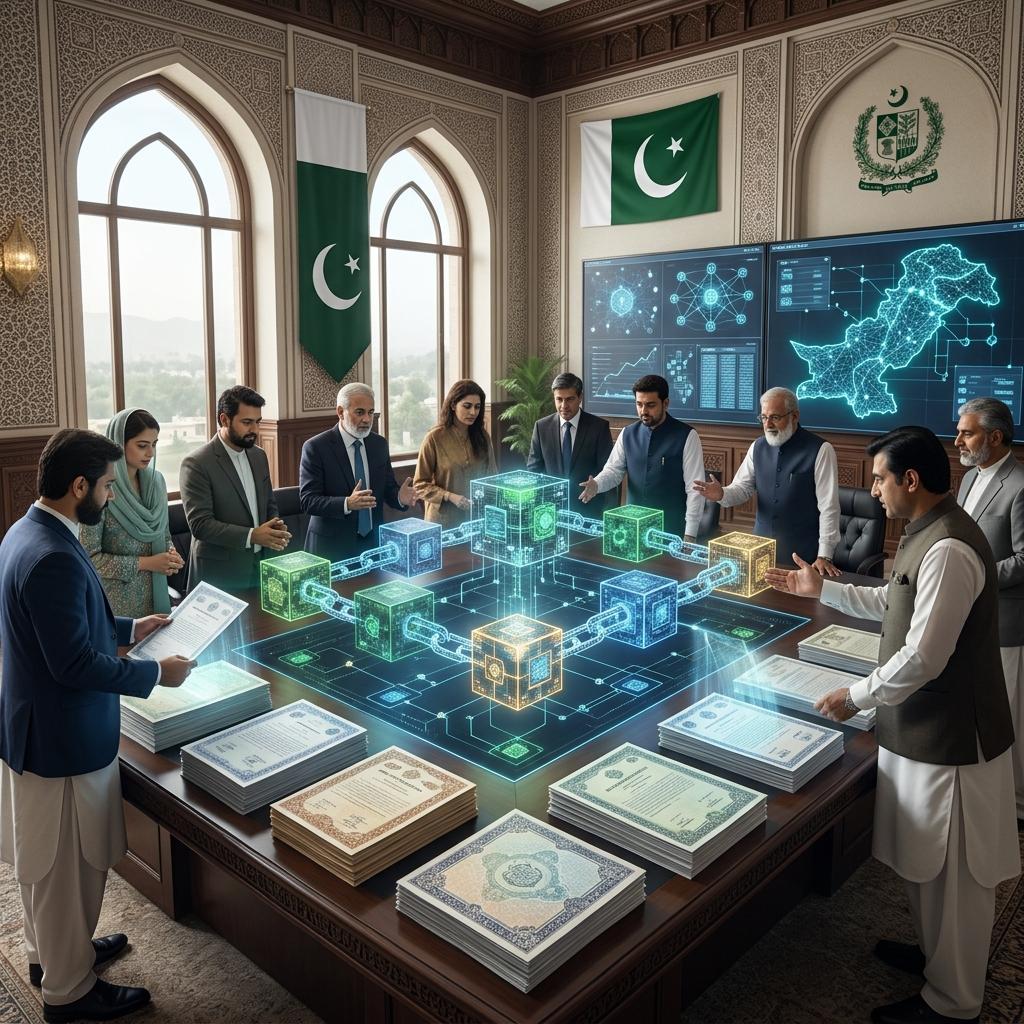
Pakistan is reviewing a plan to “tokenize” its existing Eurobond debt, creating digital representations of the bonds on a blockchain. Enabled by the Virtual Assets Act 2026 and regulator PVARA, it could modernize how the debt is recorded, settled, and accessed by investors. It’s early-stage and exploratory, pending Cabinet approval before any request for proposals.
Here’s a development that sounds futuristic, and is genuinely interesting: Pakistan is exploring putting its government debt on a blockchain. Finance Minister Muhammad Aurangzeb recently said the government is reviewing a plan to “tokenize” Pakistan’s existing Eurobond debt, part of a broader push to modernize the country’s financial system using digital-asset technology.
If that sentence contains words you’re not sure about (“tokenize,” “Eurobond,” “blockchain”), you’re not alone. This is a jargon-heavy topic, but the underlying idea is more understandable than it sounds, and potentially significant for Pakistan. So let’s break it down clearly: what tokenization actually means, what Pakistan is proposing and why, the potential benefits, and, importantly, the honest reality that this is still an early-stage plan being studied, not a done deal. Here’s what it all actually means. (A note upfront: this is an explainer for general understanding, not investment advice, and it concerns early-stage plans that may change, more on that throughout.)
Let’s define the key terms simply, because understanding them makes the whole thing clear. Three concepts matter here.
First, a Eurobond: despite the name, this isn’t about Europe. A “Eurobond” is simply a bond (a form of debt/loan) that a country like Pakistan issues to international investors, usually in a foreign currency like US dollars, to borrow money. Pakistan regularly issues Eurobonds to raise funds (for example, it raised $3 billion through a Eurobond issuance in September 2026). So “Pakistan’s Eurobond debt” just means the money Pakistan has borrowed from international investors via these dollar bonds, which it pays back with interest.
Second, blockchain: a blockchain is a secure, shared digital ledger (record-keeping system) that records transactions and ownership in a way that’s transparent, hard to tamper with, and doesn’t rely on a single central record-keeper. It’s the technology underlying cryptocurrencies, but it has many other potential uses, including for financial assets.
Third, tokenization: this is the key one. Tokenization means creating a digital representation (a “token”) of an asset on a blockchain. Instead of a bond existing only as a traditional paper or electronic record in conventional systems, a tokenized bond exists as a digital token on a blockchain, so its ownership and transactions can be recorded and managed digitally on that shared ledger. So, putting it together: “tokenizing Pakistan’s Eurobond debt” means taking the government’s existing dollar bonds and creating blockchain-based digital versions of them, so they can be recorded, held, and traded digitally on a blockchain. That’s the core idea. Now, why would Pakistan want to do that?
Let’s be precise about what’s happening, because the details (and the stage it’s at) matter. Finance Minister Aurangzeb, speaking at a “Dialogue on Digital Assets and the Future of Banking” (organized by the Pakistan Banks’ Association with LUMS), said the government is reviewing the possibility of tokenizing Pakistan’s existing Eurobond debt, and is seeking Cabinet approval before inviting proposals (issuing a “request for proposals,” or RFP) for the initiative.
A few important specifics. It’s about existing Eurobond debt: the plan concerns Pakistan’s already-issued Eurobonds (the dollar debt it already owes), exploring whether these can be managed/represented using blockchain technology. It’s part of a broader vision: beyond Eurobonds, Pakistan has been exploring tokenizing other instruments too, like Naya Pakistan Certificates (savings instruments for overseas Pakistanis) and even applications for remittances and Roshan Digital Accounts, all aimed at modernizing how money and financial assets move. It’s enabled by a new legal framework: this is possible because Pakistan established the Virtual Assets Act 2026, creating the Pakistan Virtual Assets Regulatory Authority (PVARA) to license and supervise virtual-asset businesses, moving the country from an earlier crypto-prohibition stance toward a regulated, supervised framework (as we’ve covered). And crucially, it’s at an early, exploratory stage: the minister was clear that the government is still reviewing it and needs Cabinet approval before even issuing the RFP. Officials have not disclosed a timeline, which bonds would be included, or what share of the debt it would cover, those details remain open. So what’s being proposed is a serious exploration of modernizing Pakistan’s debt (and broader financial instruments) using blockchain tokenization, within its new digital-asset framework, but it’s a plan under study, not a finalized program.
Let’s look at why this is attractive, because tokenization offers genuine potential advantages that explain the government’s interest. If done well, tokenizing debt and financial instruments could bring several benefits.
Consider them. Faster settlement: tokenized assets on a blockchain can potentially be settled (ownership transferred and finalized) much faster, even near-instantly, than traditional systems that can take days, improving efficiency. Broader investor access: tokenization could make it easier for more investors, potentially including smaller retail investors and overseas Pakistanis, to access and hold these instruments, by making them more divisible and easier to trade digitally (this is a key hoped-for benefit, especially for engaging the diaspora). Lower costs and friction: digitizing and automating processes (via blockchain and “smart contracts”) could reduce the costs, intermediaries, and friction involved in issuing, managing, and trading these instruments. Modernized capital markets: it positions Pakistan’s financial markets to participate in the emerging “financial infrastructure of the new economy,” keeping pace with global innovation in digital finance. Transparency and efficiency: blockchain’s transparent, tamper-resistant record-keeping could improve the transparency and efficiency of managing these instruments. And new opportunities: successfully tokenizing instruments like Naya Pakistan Certificates could make them more accessible and attractive to overseas Pakistanis, potentially boosting the remittances and investment inflows Pakistan depends on (remittances reached around $41.6 billion in the previous fiscal year, so making diaspora investment easier is strategically valuable). So the appeal is real: tokenization could make Pakistan’s debt and financial instruments faster, cheaper, more accessible, and more modern to manage and trade. That’s a genuinely worthwhile goal, and why the government is exploring it.
In keeping with honest analysis, this is crucial: this is a plan being studied, not an announced, finalized, or imminent program, and it’s important not to overstate it. Several honest points matter.
Be clear on the stage. It’s under review: the Finance Minister said the government is reviewing the possibility and is seeking Cabinet approval before even issuing a request for proposals, so it’s at an early, exploratory stage, not a decision taken. Key details are undecided: officials have not disclosed a timeline, which specific Eurobonds would be included, or what share of the debt it would cover, these fundamental details remain open. Multiple stages lie ahead: realistically, several steps still need to happen (Cabinet approval, then an RFP, then selecting a technology partner, then actual design and implementation) before anything is real. It’s complex: tokenizing sovereign debt involves significant technical, legal, regulatory, and financial complexity, and must integrate with existing international bond-market systems, this is genuinely hard, careful work. And outcomes are uncertain: as with any ambitious financial-innovation plan, there’s no guarantee it proceeds as envisioned, or delivers all the hoped-for benefits; it could change, slow, or stall. So the honest framing is: this is a genuinely interesting, forward-looking exploration that signals Pakistan’s serious intent to modernize its finance using digital-asset technology, but it’s early-stage and exploratory, and should be understood as a plan under study, not a sure thing or an imminent reality. Watch it develop through official channels, and keep expectations measured. Promising direction, early days.
This plan makes more sense when you see it as part of a bigger shift, which is worth understanding. Pakistan has been on a notable journey with digital assets and blockchain over the past couple of years, moving from caution to cautious embrace.
Here’s the arc. Not long ago, Pakistan’s stance on crypto and digital assets was largely prohibitive and uncertain. Then, as we’ve covered, Pakistan established a statutory framework through the Virtual Assets Act 2026, creating PVARA (the Pakistan Virtual Assets Regulatory Authority) to license and supervise virtual-asset service providers, moving from “prohibition and regulatory ambiguity toward supervised participation.” The State Bank has provided a conditional route for banking services to PVARA-licensed businesses (with due diligence and client-fund safeguards). And now, the government is exploring concrete applications of this framework, like tokenizing Eurobonds, Naya Pakistan Certificates, and remittance-related instruments. So the Eurobond tokenization plan isn’t a random idea; it’s a logical next step in Pakistan’s broader move to build a regulated digital-asset ecosystem and apply blockchain to modernize its financial system. It reflects a government increasingly willing to engage with, and try to harness, these technologies in a supervised way. Seen in this context, it’s part of a coherent (if ambitious and still-developing) strategy to modernize Pakistani finance, not an isolated experiment. That bigger picture is encouraging, even as the specific plan remains early.
Even at an early stage, this development carries real significance.
For financial modernization, exploring tokenization signals Pakistan’s serious intent to modernize its capital markets and debt management using cutting-edge digital-finance technology, potentially improving efficiency and access.
For the diaspora and inflows, tokenizing instruments like Naya Pakistan Certificates could make investing in Pakistan easier and more attractive for overseas Pakistanis, potentially boosting the remittances and inflows the economy relies on.
For the digital-asset ecosystem, concrete applications like this give real purpose to Pakistan’s new Virtual Assets Act and PVARA framework, helping build a legitimate, regulated digital-finance sector.
For global positioning, engaging with tokenization keeps Pakistan in step with a significant global trend in finance, and (as the government noted) lets it represent developing economies’ interests in international digital-finance discussions.
The key takeaway is that Pakistan exploring the tokenization of its Eurobond debt is a genuinely forward-looking, encouraging signal of the country’s intent to modernize its financial system using digital-asset technology, best understood as a promising early-stage exploration rather than an imminent or guaranteed program. There are two things to appreciate together. First, the direction is genuinely significant and positive: a country that recently prohibited crypto is now, within a new regulated framework (the Virtual Assets Act and PVARA), seriously exploring applying blockchain to modernize its sovereign debt, savings certificates, and remittance flows. That reflects real ambition to keep pace with global financial innovation, improve efficiency and access, and potentially engage the diaspora more effectively, all worthwhile goals. The potential benefits (faster settlement, broader access, lower costs, modernized markets) are real and meaningful. So this deserves recognition as a smart, forward-looking move worth pursuing.
Second, though, measured expectations are essential. This is explicitly a plan under review, pending Cabinet approval before even an RFP, with no timeline and key details (which bonds, how much) undecided, and several complex stages (approval, RFP, technology partner, design, implementation) still ahead. Tokenizing sovereign debt is technically, legally, and financially complex, and must integrate with existing international systems. So while the exploration is genuinely promising, it’s early days, and outcomes are uncertain; it could evolve, slow, or change significantly. The sensible way to understand it is as an encouraging signal of Pakistan’s financial-modernization ambitions and its maturing digital-asset journey, a direction worth watching and supporting, rather than a done deal to bank on. For ordinary Pakistanis (including the overseas diaspora who might eventually benefit from easier, tokenized access to Pakistani instruments), the practical stance is: find it genuinely interesting and promising, follow its development through official and credible sources, but keep expectations realistic and don’t make any decisions based on an early-stage plan. And as always with anything touching financial instruments and digital assets, this is informational, not investment advice; such areas carry risks and complexity, so rely on official information and qualified professionals. Pakistan putting its toe into tokenizing sovereign debt is a notable, hopeful sign of its financial modernization, exciting to watch, wise to understand with clear eyes. The future of finance is increasingly digital, and Pakistan is signaling it wants to be part of it. That’s genuinely worth noting, with measured optimism.
Watch for the plan’s progression through official channels: Cabinet approval, then (if approved) a request for proposals, then selection of a technology partner, and eventually design and implementation. Each step will clarify whether and how Pakistan proceeds. Watch, too, for which instruments get prioritized (Eurobonds, Naya Pakistan Certificates, remittance applications) and how the broader digital-asset framework (PVARA, SBP coordination) develops to support them.
If Pakistan executes well, tokenization could meaningfully modernize aspects of its financial system, improving efficiency, access, and diaspora engagement over time, a genuinely positive trajectory. If it stalls or proves too complex, it may remain exploratory. The pace will depend on approvals, technical and regulatory work, and sustained commitment. More broadly, this reflects Pakistan’s ongoing digital-asset journey (from prohibition to regulated engagement), which is likely to keep evolving. For now, the Eurobond tokenization plan is an encouraging early signal worth following, with realistic expectations, as Pakistan explores the digital future of its finance. Rely on official updates for how it actually unfolds.
Pakistan’s plan to explore “tokenizing” its Eurobond debt, creating blockchain-based digital versions of its government bonds, is a genuinely forward-looking signal of the country’s intent to modernize its financial system using digital-asset technology. In plain terms, it means Pakistan is studying whether to put its existing dollar-denominated government debt (and potentially other instruments like Naya Pakistan Certificates and remittance-related products) onto a blockchain, so they could be recorded, settled, and traded digitally. The potential benefits are real and attractive: faster settlement, broader investor access (including for overseas Pakistanis), lower costs, and modernized capital markets. It’s enabled by Pakistan’s notable journey from a crypto ban toward a regulated digital-asset framework (the Virtual Assets Act 2026 and PVARA), and it’s a logical next step in that evolution. But the honest, essential caveat is that this is early-stage and exploratory: the government is reviewing it, seeking Cabinet approval before even inviting proposals, with no timeline and key details (which bonds, how much) still undecided, and several complex stages ahead. So it’s a promising plan under study, not an imminent or guaranteed program. The sensible way to see it is as an encouraging, ambitious signal of Pakistan’s financial-modernization intent, worth watching and understanding, while keeping expectations measured and not making decisions based on an early-stage exploration. Pakistan is signaling it wants to be part of finance’s digital future, and tokenizing sovereign debt is a notable step in that direction. It’s a genuinely interesting development to follow, through official sources, with clear-eyed, measured optimism. The digital transformation of Pakistani finance is unfolding, one careful, exploratory step at a time.
This article is for general informational and explanatory purposes only, based on official statements and reports available as of early November 2026. The described plan to tokenize Eurobond debt is early-stage and exploratory (pending Cabinet approval and subject to change); details, timelines, and outcomes are undecided and may change, rely on official government sources (Ministry of Finance, SBP, PVARA) for the current, accurate position. This is NOT investment, financial, or legal advice, and nothing here is a recommendation regarding any bond, token, security, or digital asset. Digital assets, blockchain-based instruments, and bonds carry risks and complexity; consult qualified professionals and official information before making any financial decision. Mentions of officials and institutions are factual references based on public reporting.
Pakistan is exploring “tokenizing” its existing Eurobond debt, putting it on a blockchain. Finance Minister Muhammad Aurangzeb said on November 2, 2026 (at a Pakistan Banks’ Association-LUMS “Dialogue on Digital Assets and the Future of Banking”) that the government is reviewing the possibility and is seeking Cabinet approval before inviting proposals (issuing a request for proposals, RFP).
Key terms: A “Eurobond” (despite the name, not about Europe) is a bond a country issues to international investors, usually in a foreign currency like US dollars, to borrow money (Pakistan raised $3 billion via a Eurobond issuance in September 2026). A “blockchain” is a secure, shared, tamper-resistant digital ledger. “Tokenization” means creating a digital representation (token) of an asset on a blockchain. So tokenizing Pakistan’s Eurobond debt means creating blockchain-based digital versions of the government’s existing dollar bonds, so ownership and transactions can be recorded, held, and traded digitally.
What’s proposed: it concerns existing Eurobond debt; it’s part of a broader vision also covering Naya Pakistan Certificates (savings instruments for overseas Pakistanis) and applications for remittances and Roshan Digital Accounts; and it’s enabled by the Virtual Assets Act 2026, which created the Pakistan Virtual Assets Regulatory Authority (PVARA) to license and supervise virtual-asset businesses, moving Pakistan from crypto prohibition toward regulated participation. The State Bank has given a conditional banking route to PVARA-licensed businesses.
Potential benefits: faster settlement (near-instant vs. days); broader investor access (potentially smaller investors and overseas Pakistanis, via more divisible, digitally tradable instruments); lower costs/friction (digitization, automation, smart contracts); modernized capital markets; improved transparency; and better diaspora engagement (tokenizing Naya Pakistan Certificates could boost remittances/inflows, which reached ~$41.6 billion last fiscal year).
Honest reality (crucial): it’s early-stage and exploratory, under review, pending Cabinet approval before even an RFP. Officials have NOT disclosed a timeline, which specific bonds would be included, or what share of the debt it would cover. Several complex stages lie ahead (Cabinet approval, RFP, selecting a technology partner, design, implementation). Tokenizing sovereign debt is technically, legally, and financially complex and must integrate with existing international bond systems. So it’s a promising plan under study, not an imminent or guaranteed program; outcomes are uncertain.
Context: it fits Pakistan’s broader digital-asset journey, from a largely prohibitive crypto stance to the regulated Virtual Assets Act/PVARA framework, now exploring concrete applications like tokenization. Takeaway: a genuinely forward-looking, encouraging signal of Pakistan’s financial-modernization intent and maturing digital-asset journey, best watched with measured expectations through official sources. Explainer/informational, NOT investment advice; early-stage plan may change; rely on official sources (Ministry of Finance, SBP, PVARA); digital assets and bonds carry risks.